UAE Set to Introduce Major New Tax Rule From October 1
Businesses across the UAE have been advised to carry out more extensive due diligence on their suppliers as new VAT compliance requirements approach.
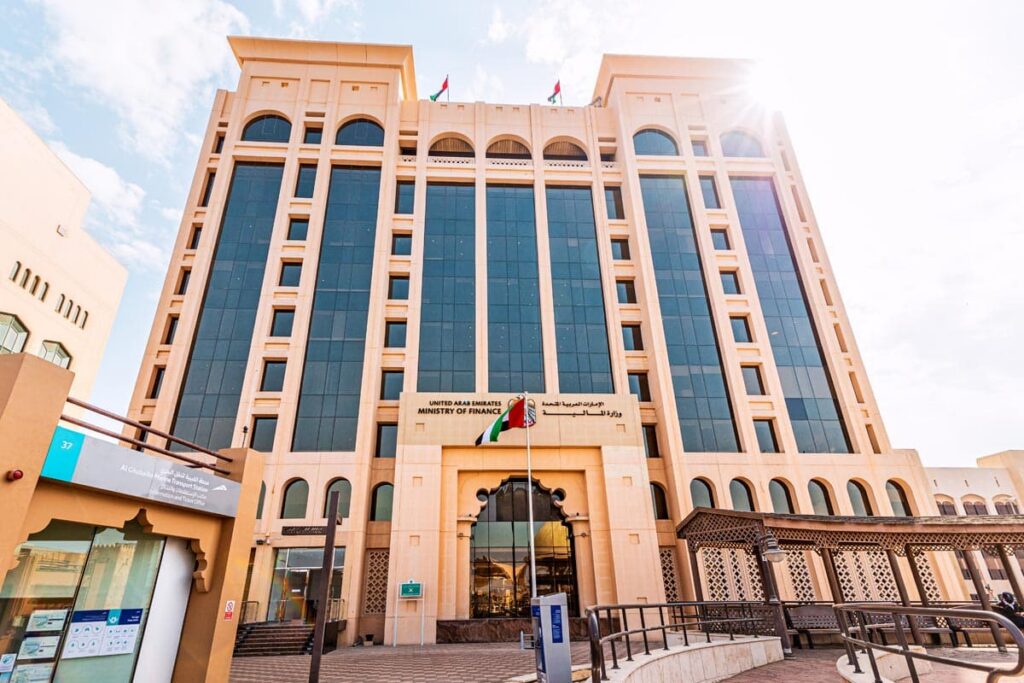
The warning comes from the UAE’s Federal Tax Authority (FTA), which is introducing a significant new tax rule from next month.
From October 1, the FTA will have the authority to reject a business’s VAT refund claim if it suspects that the goods purchased were involved in tax avoidance or evasion at some point in the supply chain.
VAT is a 5 per cent levy applied to most goods and services in the country. Businesses have generally been able to recover the VAT paid on eligible purchases through their tax returns.
Under the new rules introduced by the FTA, authorities will have greater powers to deny VAT refund claims.
Legal experts have highlighted one of the key challenges posed by the reforms: businesses may no longer need to have been directly aware of wrongdoing for their VAT claims to be rejected.
This means a company could be unaware of tax evasion occurring elsewhere in its supply chain, yet still face a rejected VAT claim.
The approach effectively places greater emphasis on whether a business “should have known” about potential irregularities.
What changes do businesses need to make?
Businesses across the UAE will need to conduct significantly closer checks on their suppliers. Experts recommend a two-layered approach to supplier due diligence.
Companies will need to verify a supplier’s identity when they first begin working with them and repeat the verification process every 12 months.
Businesses should also monitor potential warning signs, including changes in a supplier’s address, the departure or movement of key employees, and transactions that appear unusually large compared with the supplier’s size and scale.
For larger commercial relationships, UAE businesses dealing with a supplier that provides goods or services worth more than $102,000 (AED 375,000) will need written confirmation from a UAE bank that the supplier maintains an account with the bank.
Another key change concerns cash payments, which will now need to be properly documented.
Companies will also be required to formally record who conducts the supplier checks, who reviews them and who is responsible for overseeing the overall process.